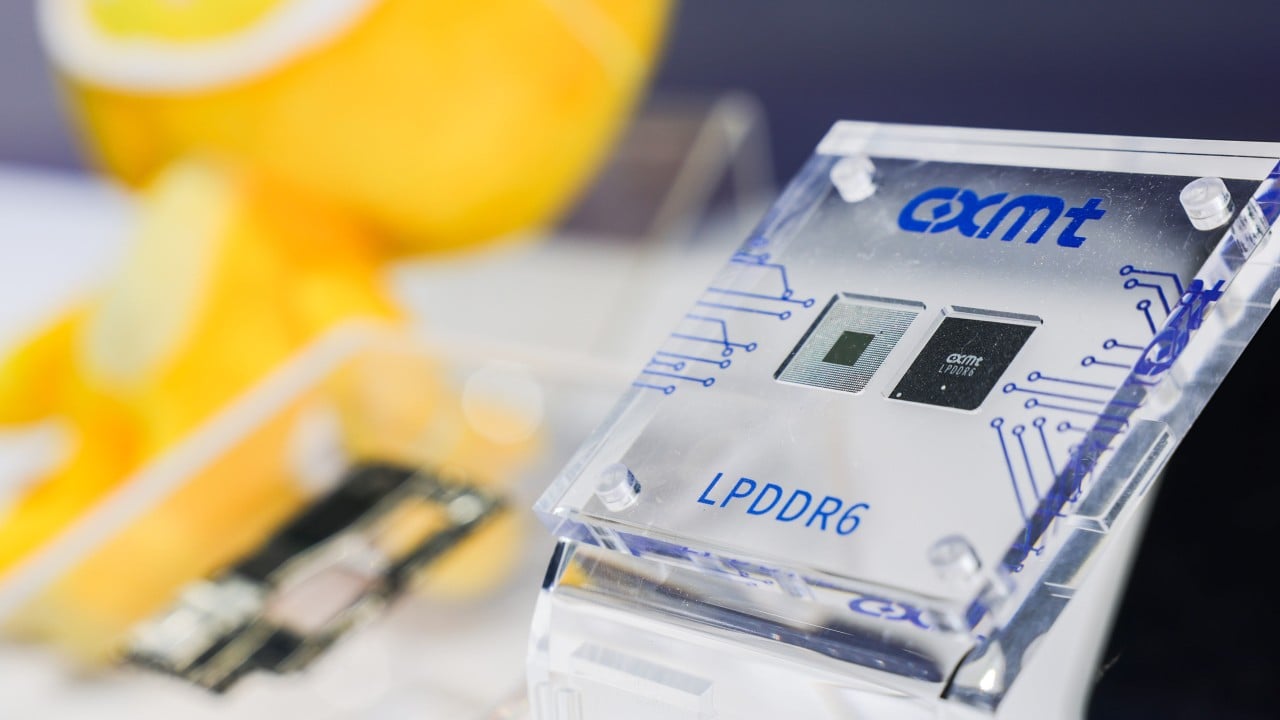
The deployment of 34.9 billion yuan, equivalent to approximately 5.2 billion United States dollars, by ChangXin Memory Technologies into dynamic random-access memory capacity expansion signals an aggressive pivot toward structural self-sufficiency in semiconductor fabrication. Rather than viewing this financial injection as a simple corporate growth initiative, industry observers must deconstruct it as an exercise in sovereign supply chain engineering. The capital allocation structure targets not merely volumetric output expansion, but a fundamental realignment of the equipment procurement matrix. By directing capital toward domestic original equipment manufacturers and in-house testing protocols, the organization is altering the cost functions and operational risk parameters governing memory production inside mainland markets.
To understand the mechanics of this expansion, one must examine the capital expenditure distribution. Semiconductor fabrication facilities operate under severe fixed-cost burdens where tool depreciation dictates unit economics. When a memory manufacturer commits billions of dollars to cleanroom expansion and wafer processing gear, the choice of vendor dictates both initial capital expenditure and long-term operational expenditure. Historically, mainstream dynamic random-access memory production relied heavily on lithography, etching, and deposition tools sourced from United States, Japanese, and European market leaders. By shifting procurement preference toward domestic equipment suppliers, the operational calculus changes. Local toolmakers receive the necessary capital feedback loops required to accelerate their R&D cycles, while the memory producer absorbs short-term yield risks in exchange for long-term supply chain security.
The economic friction of transitioning to unproven domestic semiconductor equipment involves several measurable vectors. First, tool throughput—measured in wafers per hour—often lags behind mature foreign equivalents during early-generation deployments. Second, mean time between failures for locally produced etching and cleaning systems requires rigorous, iterative engineering updates inside active production lines. Third, particle contamination rates must meet strict sub-nanometer thresholds to maintain functional die yields on advanced nodes such as fifth-generation dynamic random-access memory architectures. By absorbing these friction points within a massive capital expenditure cycle, the enterprise acts as an industrial incubator. The financial commitment provides domestic equipment vendors with the revenue streams required to fund iterative engineering fixes that would otherwise take decades to achieve through academic research alone.
The output targets extend far beyond basic commodity memory. Commercial validation cycles for advanced server memory, including double data rate five architectures and low-power variants utilized in mobile form factors, require stringent qualification processes with major cloud service providers and consumer electronics brands. When high-volume buyers such as Tencent and ByteDance integrate domestically produced memory modules into enterprise server farms, they validate the reliability of the underlying silicon. This validation breaks the circular dependency wherein buyers avoid unproven local components due to reliability concerns, and manufacturers fail to mature their products due to lack of commercial volume. The capital injection accelerates this feedback loop by underwriting the massive fixed costs associated with high-volume test and packaging infrastructure.
Examining the operational infrastructure reveals a deliberate strategy to internalize quality control and failure analysis. A significant portion of the capital expenditure is dedicated to in-house testing facilities. In traditional semiconductor models, outsourcing backend testing to specialized assembly and test houses is common practice. However, when navigating strict trade controls and export restrictions on advanced diagnostic hardware, reliance on external testing partners introduces severe operational vulnerabilities. By building proprietary testing pipelines, the organization retains complete visibility over defect clustering, parametric yield loss, and thermal dissipation characteristics. This visibility enables process engineers to trace yield anomalies back to specific chamber conditions in upstream deposition tools, creating a closed-loop optimization system that operates independently of foreign technical support.
The financial architecture supporting this multi-billion-dollar buildout relies heavily on liquidity derived from capital markets and strategic state-backed equity funding. Moving toward an initial public offering provides the institutional balance sheet strength required to sustain multi-year capital burn rates without relying entirely on short-term debt instruments. Semiconductor manufacturing is notoriously capital-intensive, characterized by long gestation periods before factories reach full utilization. By converting private equity and state support into public market valuation, the enterprise shifts financial exposure to institutional investors while securing a permanent channel for future capital raises. This financial buffering is essential for maintaining aggressive research and development spending during cyclical downturns in the memory market, where spot prices frequently fall below marginal production costs.
The strategic implications for the global memory market extend into pricing power and supply elasticity. Established industry leaders in South Korea and the United States have historically maintained oligopolistic control over dynamic random-access memory pricing through disciplined capacity management. The emergence of a well-funded, state-backed domestic champion with a mandate to utilize local equipment disrupts this traditional pricing equilibrium. Even if early-generation domestic output targets lower-tier consumer applications initially, the steady displacement of imported silicon in domestic supply chains frees up global supply for other markets while establishing a permanent floor for local production capacity. This bifurcation of the memory supply chain creates two distinct economic ecosystems operating under separate cost structures and regulatory constraints.
Equipment suppliers within the domestic ecosystem face unprecedented operational demands. Meeting the rigorous specifications of a high-volume memory producer requires scaling precision manufacturing capabilities that were previously dependent on imported sub-components, such as specialized optical lenses, high-frequency radio frequency generators, and ultra-pure ceramic chamber linings. As the enterprise channels billions of dollars into these local suppliers, it creates a cascading effect across the entire upstream industrial base. Precision engineering firms that previously served low-margin industrial sectors are forced to upgrade their quality management systems, cleanroom standards, and metallurgical tolerances to meet semiconductor-grade requirements. This industrial upgrading represents the true objective of the capital push: transforming a fragmented network of niche component makers into a cohesive, self-sustaining high-technology manufacturing cluster.
The operational risks embedded within this strategy are substantial and warrant precise quantification. Subsidized capital deployment does not automatically guarantee technological parity at advanced nodes. While scaling capacity for mature and intermediate nodes is primarily a function of capital expenditure and facility construction, scaling sub-nanometer lithography and advanced packaging requires fundamental physics breakthroughs in materials science and quantum efficiency. If domestic equipment suppliers experience persistent bottlenecks in producing reliable deep ultraviolet or extreme ultraviolet alternatives, the capital expenditure risks yielding high-volume production lines optimized for obsolete architectures. The enterprise must continuously balance the political imperative for domestic sourcing against the commercial necessity of maintaining performance parity with global competitors.
Navigating this dual mandate requires a pragmatic operational roadmap. Management must segment production lines to isolate unproven domestic tools from stable, revenue-generating legacy nodes, ensuring that overall facility cash flow remains positive during the transition phase. Concurrently, engineering teams must establish rigorous failure-reporting feedback loops with local equipment vendors, treating every line stoppage as an empirical data point for rapid design iteration. The long-term viability of the enterprise depends entirely on whether these domestic equipment suppliers can compress a thirty-year Western learning curve into a fraction of the time through sheer capital intensity and coordinated industrial planning. To achieve this, leadership must enforce strict performance metrics across all local tier-one suppliers, penalizing chronic delivery delays and technical underperformance regardless of political alignment. The ultimate measure of success will not be the total capital expended or the square footage of cleanroom space constructed, but the sustained reduction in defect density per square millimeter at commercial scale.