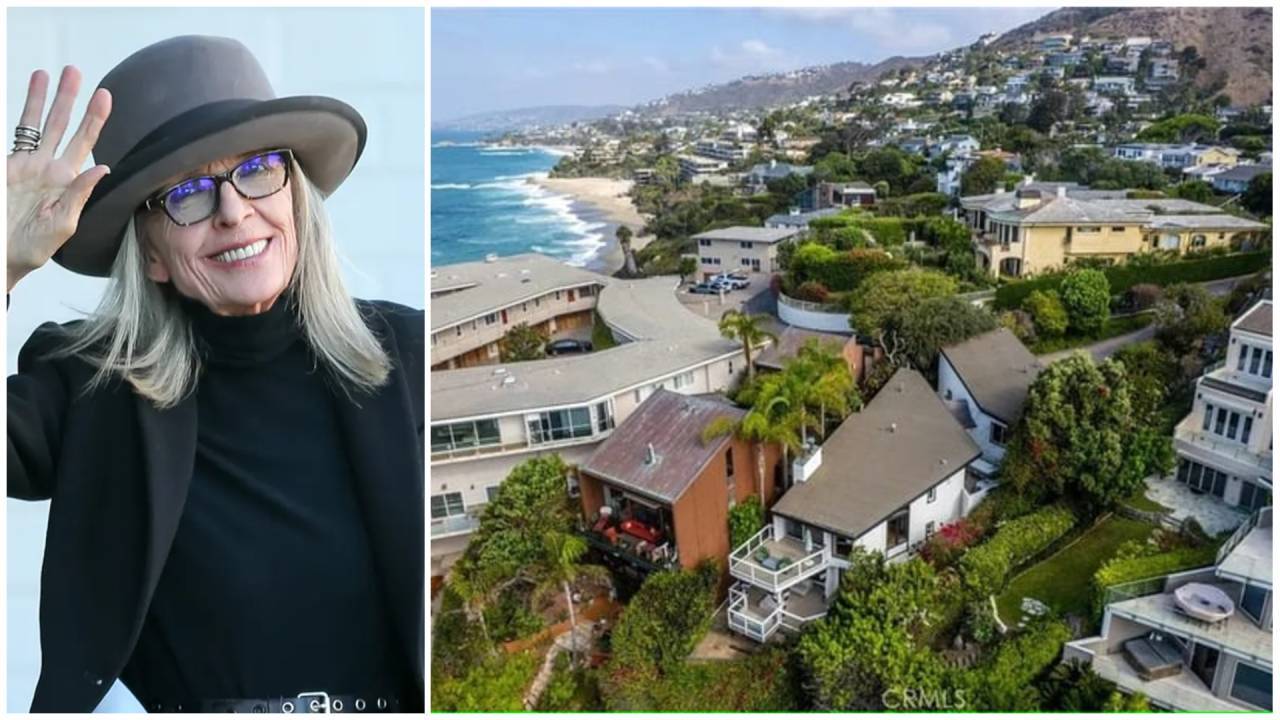
The Architecture of Capital and Margin in Coastal Real Estate
Evaluating a high-end residential transaction requires stripping away the narrative gloss of celebrity ownership and headline-grabbing price tags. When a property constructed in 1976 changes hands for $6.6 million, undergoes extensive renovation, trades again at $7.9 million, and subsequently commands a $10.3 million asking price, the trajectory offers a masterclass in asset repositioning, capital expenditure efficiency, and buyer demand elasticity in prime coastal submarkets. Understanding this lifecycle demands a rigorous deconstruction of structural obsolescence, renovation cost functions, brand-driven pricing premiums, and the severe liquidity barriers that govern eight-figure real estate.
The Structural Baseline and Functional Obsolescence
A 1976 construction date in coastal Southern California represents a distinct architectural and engineering era. Structures erected during this period frequently suffer from deep functional obsolescence. Low ceiling heights, compartmentalized floor plans, outdated seismic engineering, and mechanical infrastructure failing modern energy and efficiency standards are standard characteristics of this vintage. When an investor or high-net-worth individual acquires such an asset at a $6.6 million basis, the purchase price reflects land value and locational scarcity rather than the underlying physical improvements.
The parcel dictates the floor of the asset's value, while the physical structure represents a depreciating liability requiring a massive capital injection. In prime coastal enclaves such as Laguna Beach, land is a strictly finite commodity. Existing housing stock cannot be expanded horizontally due to geographic topography and restrictive municipal zoning regulations. Value creation must therefore occur through vertical optimization, interior reconfiguration, and aesthetic modernization.
The initial $6.6 million purchase price is not an entry into a finished product; it is the acquisition of raw spatial potential secured by geography. The primary risk at this entry point is miscalculating the capital required to bridge the gap between 1970s functional limitations and contemporary buyer expectations. If the structural envelope requires extensive remediation, the initial basis effectively shrinks the profit margin before a single hammer swings.
The Renovation Cost Function and Margin Compression
Transforming a vintage home into a marketable luxury asset requires capital expenditure that extends far beyond cosmetic surface updates. Structural engineering modifications, envelope sealing, roof replacement, mechanical overhauls, and interior gutting create a complex cost function where supply chain friction, labor shortages, and municipal permitting delays erode expected margins. When the property was sold for $7.9 million following its initial transformation, the gross delta of $1.3 million must be evaluated against transaction costs, holding expenses, property taxes, financing costs, and direct construction outlays.
In high-end residential renovation, gross margin is frequently deceptive. Real estate transaction friction—including brokerage fees, transfer taxes, title insurance, and closing costs—typically consumes five to eight percent of the gross exit value. When factoring in construction loan interest, builders' risk insurance, and extended holding periods caused by regulatory bottlenecks, a $1.3 million nominal spread can easily compress into a narrow net yield.
The decision to exit at $7.9 million indicates either a strategic realization of target internal rate of return or an assessment that further capital deployment would yield diminishing marginal returns. The seller locked in liquidity rather than chasing an unproven ceiling in that specific market cycle. Capital preservation and velocity of money often dictate that realizing a clean gain is superior to holding an asset through prolonged renovations in an uncertain macroeconomic environment.
The Provenance Premium and Brand Equity in Residential Assets
Property transactions involving prominent cultural figures introduce an intangible variable into asset valuation: celebrity provenance. When an asset is associated with a recognized public figure known for distinct architectural taste, market participants often conflate personal brand equity with intrinsic real estate value. However, empirical analysis of celebrity-owned real estate reveals a nuanced reality. Provenance can accelerate marketing velocity and generate premium initial exposure, but it rarely sustains an inflated valuation in the absence of fundamental architectural merit.
The transition from a $7.9 million exit to a subsequent $10.3 million listing highlights the separation between brand-driven pricing and open-market price discovery. A subsequent owner or speculator attempting to command a $10.3 million price tag is testing the upper boundary of buyer demand elasticity. If the physical structure and location do not independently justify the valuation, the historical association with a celebrity functions as a temporary marketing hook rather than a permanent valuation floor.
Luxury buyers at the ten-million-dollar threshold evaluate square footage, finish quality, privacy, and view corridors with clinical detachment. Provenance attracts initial eyeballs, but underwriting validates the transaction. If the underlying asset lacks the spatial volume, high-end finishes, and flawless indoor-outdoor integration expected at this price point, the celebrity connection fails to bridge the valuation gap.
Supply Elasticity and Price Discovery at the Ten-Million Threshold
Crossing the ten-million-dollar threshold in coastal submarkets shifts the asset into a highly selective tier of buyer liquidity. Below eight million dollars, the buyer pool includes successful professionals, corporate executives, and regional entrepreneurs. Above ten million dollars, the target demographic contracts significantly, shifting toward ultra-high-net-worth individuals with global asset allocation strategies. At this level, market velocity slows down, and inventory competition intensifies.
The $10.3 million asking price for the Laguna Beach property reflects an aggressive bet on localized supply scarcity. Prime coastal enclaves in Orange County experience minimal new construction. Buyers seeking modern architectural design integrated with ocean views face a severe shortage of turnkey inventory. Sellers who successfully command eight-figure prices typically offer uncompromising execution—flawless spatial flow, hyper-private settings, and top-tier material specifications.
The delta between the $7.9 million sale and the $10.3 million listing tests whether the recent transformation achieved the elite standard required to clear this liquidity barrier. In high-end real estate, pricing above ten million dollars is not a linear extrapolation of square footage costs. It is a discrete tier governed by psychological factors, prestige, and the availability of alternative assets in rival coastal markets such as Newport Beach, Corona del Mar, or Malibu.
Risk Architecture and the Downside of Speculative Upgrades
Speculative real estate transformation carries asymmetric downside risk, particularly when entering at a multi-million-dollar basis. Unlike commercial real estate, where valuations are strictly tethered to net operating income and capitalization rates, luxury residential pricing is governed by subjective emotion and macro-wealth fluctuations. When interest rates rise or equity markets experience contraction, high-end discretionary spending freezes.
A property that underwent significant capital modification to reach a $7.9 million exit, only to be repositioned at $10.3 million shortly thereafter, embodies high exposure to execution risk and holding cost drag. If the market absorbs the $10.3 million price point, it validates the thesis that the original transformation unlocked latent land value. If the asset lingers on the market, price reductions become inevitable, signaling to prospective buyers that the initial valuation was misaligned with current liquidity realities.
Luxury real estate does not forgive over-capitalization. Every dollar spent on custom finishes must translate directly into perceived utility for the marginal buyer. When improvements are overly idiosyncratic or tailored to a specific celebrity aesthetic, the addressable buyer pool shrinks further, increasing the duration of capital lockup and eroding net realized returns.
Strategic Capital Deployment and Execution Playbook
To maximize the probability of execution at the upper tier of coastal residential markets, market participants must decouple personal provenance from structural underwriting. Capital allocation should prioritize structural permanence, floor plan efficiency, and timeless material selection over transient design trends.
When evaluating a repositioning play on vintage housing stock, investors must establish a strict ceiling on renovation budgets relative to localized comparable sales, ensuring that carrying costs do not outpace natural appreciation curves. Execute clean exits when target risk-adjusted returns are met, rather than speculating on aggressive price appreciation driven solely by past ownership history or temporary market exuberance. True asset value in coastal real estate is forged at the intersection of structural integrity, scarce geography, and uncompromised execution.